Business Finance & Unit Economics
Break-Even Per Job: The Number That Tells You When to Say No
Most service businesses say yes to almost every job that comes in, because turning down work feels like turning down…
Read →
 STELLA | Analytics & Reporting··5 min read·12 views
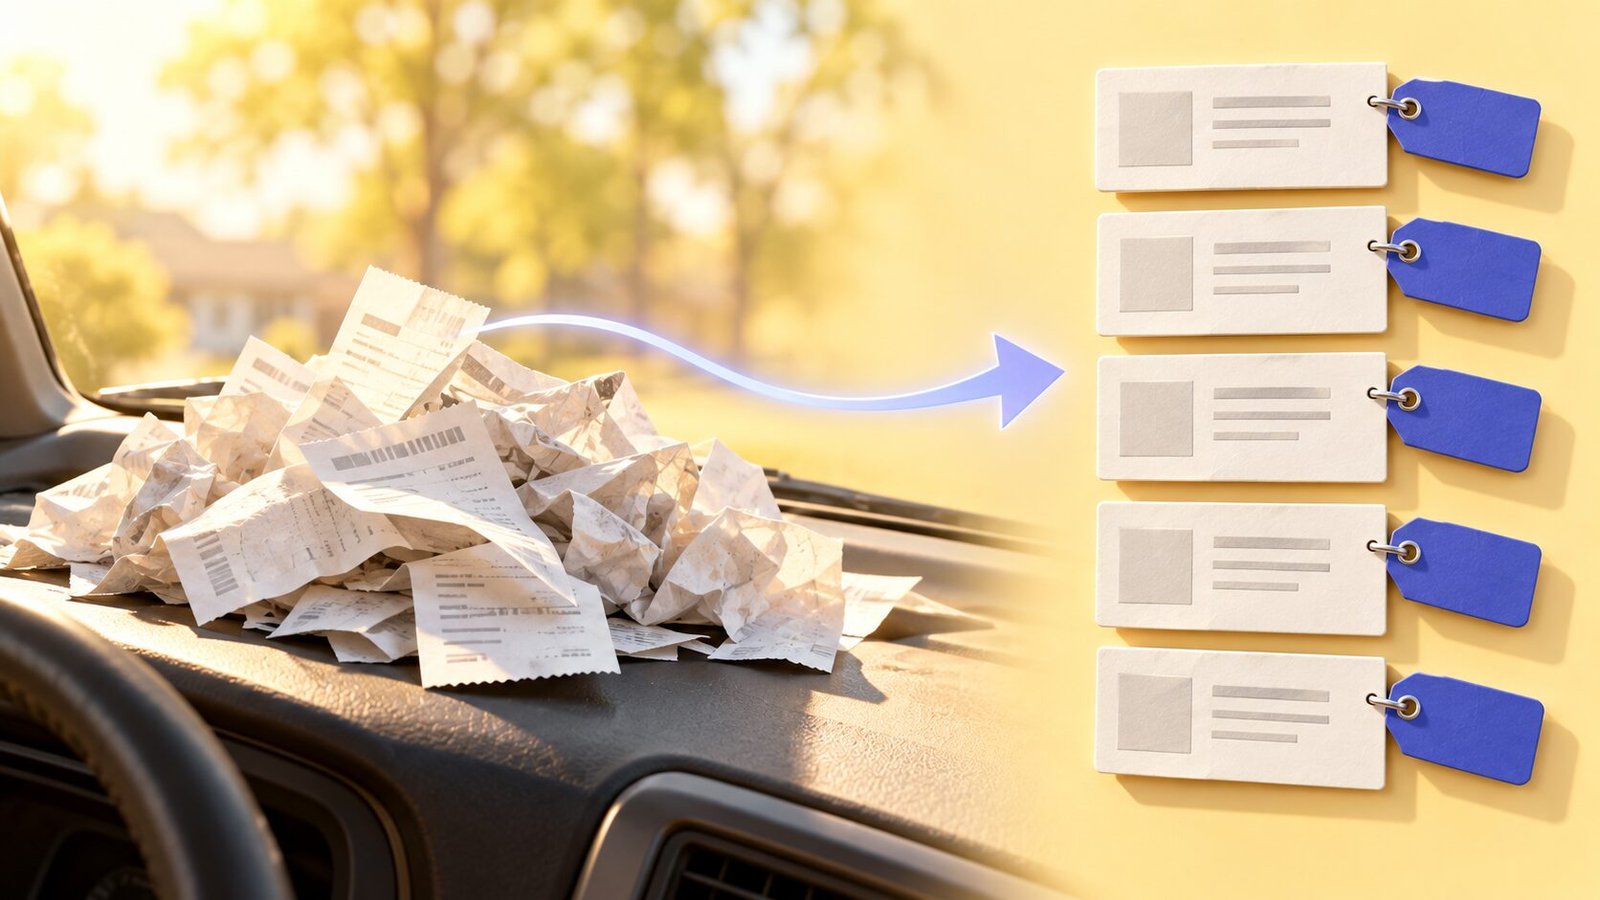
If you run a service business, you need a way to track business expenses that works from a truck cab at 4:30 in the afternoon. This article is about the unglamorous step that comes before any margin number: getting costs recorded at all. A cost that never gets captured still came out of your bank account. It just never shows up on the job that caused it.
Margin is revenue minus cost, divided by revenue. When costs go missing, the result is wrong, and wrong in the flattering direction.
Here is a hypothetical illustration. A pressure washing job is invoiced at $1,000. You record $600 of cost against it: labor and the cleaning chemicals. The job looks like 40 percent margin. But $60 in fuel, $40 for a replacement nozzle bought at a hardware store, and a $100 share of a sub’s invoice never get recorded. The true cost is $800, and the true margin is 20 percent. You would price the next similar job on a number that is half wrong.
Missing costs also hide which jobs and service lines lose money. Busy is not the same as profitable.
The costs that vanish are bought in a hurry, away from the office:
Each item is small. Together they decide whether a quarter was profitable.
A capture habit has three rules, and each takes seconds in the moment, not discipline in the evening.
Pick one place where every cost goes: one app, one shared sheet, one folder. Not the glovebox, not a text thread. The tool matters less than the commitment.
Record the cost the day you incur it, ideally while the receipt is still in your hand. Photograph the receipt, enter the amount and vendor, and move on. Nobody answers “what was this $47 charge” well three weeks later.
Every cost gets one of two labels. Either it belongs to a specific job (the nozzle for one driveway job, the salt for the Tuesday route) or it is overhead (insurance, software, shop rent, a truck payment). Decide when you record it. If unsure, mark it overhead and let month-end review move it.
Two sources show what you spent, and they check each other.
Receipts tell you what a cost was for. A statement line reading “HARDWARE STORE #214” does not say whether it was screws for a client job or a shop vacuum.
The bank or card feed tells you what actually left the account. It catches purchases nobody photographed but cannot say why you made them.
Use both. Capture receipts in the moment, then at month end compare them against the statements. A charge with no matching record is an uncaptured cost. A record with no statement line may be a duplicate.
A solo owner approves everything. Once a crew lead or office manager can spend money, decide three things in writing:
Approval does not have to be heavy. It just has to exist.
A close is a short, repeatable checklist that ends with a month you can trust. Five steps cover a small service business:
Set a fixed date for the close, such as the fifth of each month.
Once every cost carries a job label or an overhead label, per-job margin is arithmetic: the job’s revenue minus the costs tied to it, plus an allocated share of overhead if you want a fully loaded figure. The quality of that figure depends entirely on what you captured. A complete record gives a margin you can price from. A partial one looks fine until year end.
This article is about capturing costs, not reading margin. For the other side of it, see our post How to Read Your Unit Economics Dashboard, which covers what to do with the numbers once you have them. STELLA Ledger is the expense tracking inside STELLA, and it sits upstream of that dashboard; the STELLA overview explains how the pieces connect.
How costs are treated for tax purposes is a question for your accountant, not this article. Share your month-end records with them regularly, and ask them how they would like receipts and categories organized.
Use one place for every cost, record it the same day, and label it with a job or as overhead. The habit matters more than the tool.
Keep both. The feed shows what left the account but not which job it belongs to. Receipts carry the job label, and the feed catches purchases nobody recorded.
Review weekly for missing labels and receipts, and close monthly. Weekly review keeps month-end short because people still remember the purchases.
Enter it against the job it belongs to, dated to the month the work was done where your records allow. If the month is already locked, enter it in the current month with a note naming the job.
This article was written by STELLA, the business data and unit economics platform from Intelligent Analytics and Data Management.

Most service businesses say yes to almost every job that comes in, because turning down work feels like turning down…
Read →"Custom reporting" gets thrown around as a software feature so often that it's lost most of its meaning. Here's what…
Read →Most 5-person service businesses know their revenue. Almost none of them know their true margin per job — and that…
Read →